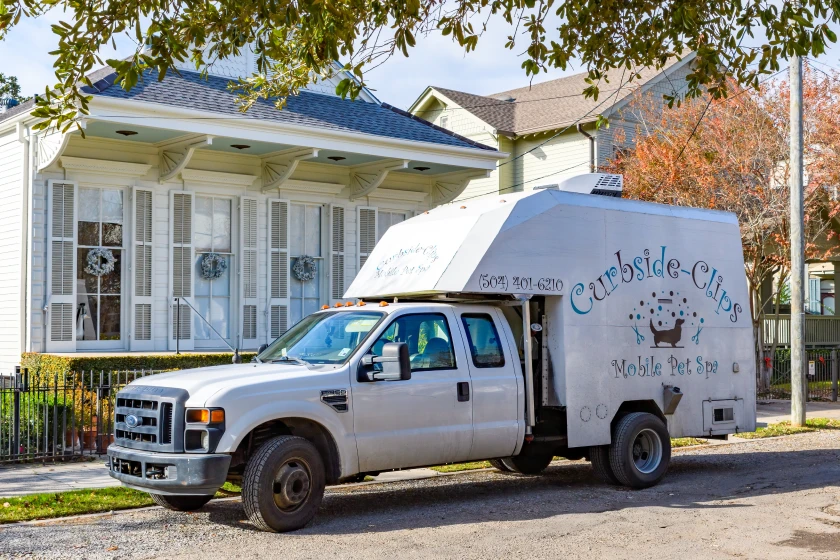
From navigating traffic to meeting anxious clients (and their owners), your day can be full of surprises. A nervous dog, a slip during a trim, or an accident on the road can happen even when you’re careful.
A few practical safety tips can help reduce mobile grooming liability risks, but when accidents happen anyway, having the right coverage can protect more than just your van.
The 6 Mobile Grooming Risks You Should Know
Some things that could go wrong on a mobile grooming job include:
- Vehicle accidents
- Damaged or stolen equipment
- Client property damage
- Pet injuries, illnesses, or escapes
- A dog injuring someone else
- Service-related mistakes
Thoughtful booking procedures, secure curbside transfers, and a tailored pet grooming insurance policy can help you manage these risks.
A Quick Look at Managing Mobile Dog Grooming Liability Risks
Use this guide before your next appointment to spot day-to-day risks, preview our prevention tips, and see which coverages your grooming business needs.
← Swipe to view table →
| The Risk | Top Prevention Tip | What Can Help Cover It |
|---|---|---|
|
Your grooming van getting into an accident
|
Make parking and driveway access questions part of your regular booking process |
Commercial auto insurance |
|
Damaged or stolen grooming equipment |
Strap down dryers, tables, and clippers before you roll, and lock up your van or trailer even during quick drop-offs |
Equipment and Inventory Coverage (Inland Marine) |
|
Damaging a client’s property |
Keep the grooming in your van (not their bathroom), unless you’re insured for house-call grooming |
General liability insurance |
|
A dog getting injured, sick, or escaping |
Outfit your workspace with non-slip mats, low-grade ramps, and secondary slip leads for added security |
Animal Bailee coverage (Pet Protection) and Veterinarian Reimbursement |
|
A dog injuring someone else while in your care |
Ask clients to keep other pets or family members inside the home during pickup and drop-off |
Animal liability (included with general liability) |
|
A client accusing you of a grooming mistake |
Use physical hair-length charts or rulers at check-in to give owners a visual reference for trims |
Professional liability insurance |
Scenario #1: You Get Into a Car Accident in Your Mobile Grooming Van
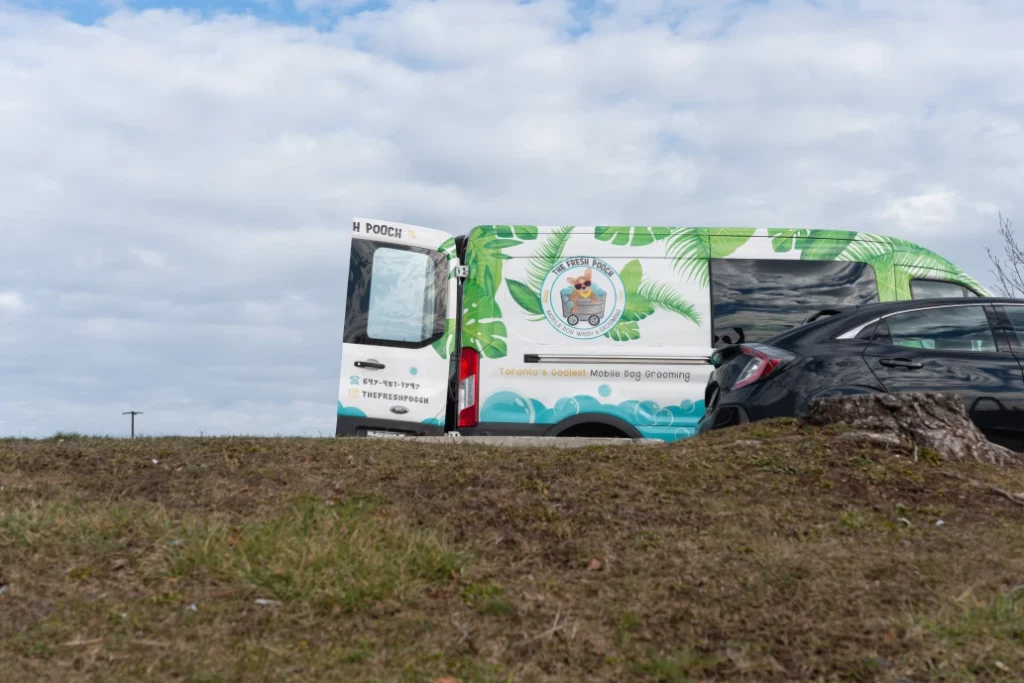
When your vehicle is your grooming salon, even a small accident can put appointments on hold. Whether it’s getting rear-ended in traffic or backing into a client’s mailbox, you may need to handle repairs to your van or someone else’s property.
How to Reduce the Risk
You can’t control other drivers, but you can maintain your vehicle and practice safe driving.
✔ Inspect your tires, brakes, lights, and mirrors before each route
✔ Allow extra space for parking, reversing, and navigating driveways
✔ Consider traffic and weather conditions before leaving for appointments
✔ Confirm the parking situation during booking
What Insurance Covers It?
Anytime you’re driving for work, you need commercial auto insurance to help cover injuries or property damage involving your grooming vehicle. Even if you’re towing a grooming trailer with a personal vehicle, personal auto insurance doesn’t typically cover business-related accidents.
Depending on your policy, it may also help pay for your own vehicle repairs.
Scenario #2: Your Mobile Grooming Equipment Is Damaged or Stolen
Your grooming tools and trailer are just as important as your vehicle. A stolen dryer or dented trailer could leave you with unexpected repairs or replacements before you can get back to work.
How to Reduce the Risk
Secure your portable grooming tools and supplies to reduce the risk of accidental damage or theft.
✔ Secure loose equipment with bungee straps to keep it from sliding when you stop or turn
✔ Store smaller tools and supplies in built-in cabinets and compartment organizers
✔ Inspect equipment regularly for damage or loose parts
✔ Lock your van or trailer whenever you step away, even if you’re just picking up or dropping off
What Insurance Covers It?
Equipment and Inventory Coverage (also known as inland marine insurance) can help you pay to repair or replace your portable grooming equipment, including your trailer, if it is suddenly damaged, stolen, or vandalized.
This coverage is a major cost-saver for accidental losses, but it doesn’t cover routine wear and tear, maintenance, or mechanical breakdowns.
🚚 What if My Grooming Equipment Gets Damaged in a Car Accident?
Your commercial auto insurance may cover permanently installed equipment, like your inverter generator, water tank, or water heater, depending on your policy. Portable gear and supplies, however, may need separate Equipment and Inventory Coverage.
Scenario #3: You Accidentally Damage a Client’s Property
Even though your grooming services happen inside your vehicle, accidents can still happen on a client’s property. Whether it’s a damaged storm door during pickup or an anxious pup knocking over a garden statue, these risks are preventable but may not be insured the same way.
How to Reduce the Risk
Always take caution when handling unpredictable dogs and hard-to-navigate properties.
✔ Keep dogs securely leashed when moving between the house and your vehicle
✔ Take extra care when opening or closing gates and doors
✔ Avoid providing grooming services inside a client’s home
What Insurance Covers It?
General liability insurance can help you cover out-of-pocket costs when you or the dog you’re grooming damage a client’s home or permanent fixtures. For example, a dog eager to be dropped off might scratch paint off the front door.
Groomers who offer house-call services are exposed to increased risks because they work inside a client’s home. Adding Broadened Property Damage Coverage can help offset costly damages to a client’s furniture or other personal belongings.
🔑 What if I Lose a Client’s House Key at Drop-off?
If you have access to a client’s home for pet pickup or drop-off, Lost Key Liability Coverage can help pay to replace locks or rekey the home if you misplace their keys.
Scenario #4: A Dog Gets Sick, Hurt, or Escapes During an Appointment
Pets can get sick from other pets, and anxious dogs can slip collars, jump off tables, or move unexpectedly. It’s your job to get the pup the care they need if something goes wrong.
How to Reduce the Risk
Being properly trained and getting grooming experience can help prevent injuries, but always be extra cautious.
✔ Conduct a pre-groom health check and verify pets are up-to-date on vaccines
✔ Use secure restraints and non-slip mats to prevent falls or escapes during grooming and transfers
✔ Keep the nearest emergency vet location saved for each route
✔ Never leave pets unattended on elevated grooming tables
What Insurance Covers It?
Animal Bailee coverage (also known as Pet Protection) can help cover claims if you’re held legally responsible for a pet getting injured, sick, or lost in your care.
If an accident occurs during an appointment and you need to take the dog to an emergency vet, Veterinarian Reimbursement Coverage may help reimburse you for those emergency costs, even if the accident wasn’t your fault.
Scenario #5: A Dog Injures People or Damages Property Outside the Van
An excited dog could knock someone over, or a nervous pup might slip its lead and go after the neighbor’s dog. You’re ultimately responsible for handling dogs (and the problems they cause) during pickup and drop-off.
How to Reduce the Risk
Keep dogs under control during pickup and drop-off to help prevent unexpected injuries.
✔ Ask owners about the dog’s temperament and behavior around strangers or other dogs
✔ Use a slip lead or short leash when transferring dogs
✔ Ask clients to keep other pets and family members inside during pickup and drop-off, away from curbside transfers
What Insurance Covers It?
Animal liability is included in PCI’s general liability coverage to help protect you from paying out of pocket if a dog in your care injures another person or their pet, or damages someone’s property.
👥 What if a Client’s Dog Hurts One of My Employees?
Your grooming liability insurance is coverage for third parties, not you or your team. Getting workers compensation coverage can help you manage the cost of employee injuries that might happen on the job.
Scenario #6: You’re Accused of Negligence or Performing the Wrong Service
If a client is unhappy, they might accuse you of performing the wrong service. Liability waivers acknowledge this risk, but they don’t replace the insurance that protects you if that client decides to sue.
How to Reduce the Risk
Clear communication with your clients can help prevent service-related mistakes.
✔ Confirm the requested grooming service and trim length using visual references, like hair-length charts
✔ Document the pet’s coat condition and any pre-existing concerns
✔ Explain potential risks before doing difficult services like dematting or extensive hand-scissoring
✔ Keep written records of customer instructions, consent, and completed services
What Insurance Covers It?
Professional liability insurance can help when a client alleges grooming mistakes, negligence, or failure to provide an agreed-upon service. This may help you cover costs like attorney fees and settlement costs.
How Much Can Mobile Dog Grooming Injuries or Accidents Cost?
Training and experience can teach you dog behavior and proper handling techniques. But when accidents happen, having the right coverage makes a major difference in what you pay out of pocket.
Here are a few pet grooming insurance claims we’ve seen and how much insurance helped cover for these business owners:
| The Claim | The Cost |
|---|---|
|
A dog jumped off a grooming table and injured its leg |
$637 |
|
A groomer’s busy schedule led to a dog attacking another dog in their care |
$1,150 |
|
After a grooming appointment, a client took their dog to the vet and found he had fluid in his lungs |
$6,963 |
Note: Claim scenario circumstances vary in nature, and similar claims do not guarantee coverage.
What Should I Do if an Accident Happens During a Mobile Groom?
If a dog gets hurt, causes damage, or another type of accident happens during a mobile grooming appointment, think safety first and follow these general steps:
- Stop the appointment: Immediately stop the service and make sure the area is secure to prevent any more harm or a potential escape
- Notify the pet owner: Talk to the pet owner immediately to explain what happened and discuss next steps
- Contact the vet: Seek prompt veterinary care when necessary, using the client’s approved veterinarian when possible
- Document the incident: After caring for the dog, record the time, location, circumstances, and relevant photos or witnesses (you may need these when filing a claim)
- Let your insurer know: If you’re insured with PCI, we make filing claims online simple and stress-free with access to licensed customer support when you need help
🚨 Remember: In an emergency, veterinary care should never be delayed to complete documentation or routine notifications. Always put everyone’s safety first to prevent further harm.
Does Your Mobile Dog Grooming Insurance Cover These Risks?
Before your next appointment, take a moment to review your safety procedures and your dog grooming liability insurance to make sure you’re prepared for the unexpected. If you find gaps in your protection, PCI’s tailored policies can help you get the coverage your business needs.
FAQs About Mobile Dog Grooming Liability Risks
What Are the Biggest Liability Risks for Mobile Dog Groomers?
Vehicle accidents, damaged or stolen equipment, client property damage, pet injuries or escapes, dogs injuring others, and service-related mistakes are the biggest liability risks for mobile dog groomers.
Does Personal Auto Insurance Cover My Mobile Grooming Van?
Not usually. Personal auto insurance typically doesn’t cover business-related driving, so you need commercial auto insurance to cover your mobile grooming van or any vehicle you’re using for work.
Do Grooming Waivers and Release Forms Actually Protect Groomers?
No. Grooming liability waivers and release forms do not protect groomers from being sued or held liable for injuries or damages. Waivers and forms simply explain the risks and show that the client acknowledged them, but they don’t eliminate your responsibility or prevent lawsuits.
What Insurance Does a Mobile Dog Groomer Need?
Mobile dog groomers need a combination of liability, vehicle, and property insurance to cover their mobile workspace, pets in their care, and their professional services.
Specialized dog grooming liability insurance can help cover claims related to your business, clients’ pets, or services, while commercial auto and equipment coverage provide additional protection for your vehicle and gear.
Jeremy Sheehy | Program Manager
Jeremy Sheehy is a Program Manager for Pet Care Insurance. His experience spans claims and commercial underwriting, and he holds a bachelor's degree from the University of Texas at Arlington along with the Chartered Property Casualty Underwriter (CPCU) designation. Jeremy believes the best insurance solutions are specialized and transparent, built through adaptability, attention to detail, and a team-first approach. He relishes helping small business owners find coverage that's both affordable and tailored to their individual needs.
Jeremy Sheehy is a Program Manager for Pet Care Insurance. His experience spans claims and commercial underwriting, and he holds a bachelor's degree from the University of Texas at Arlington along with the Chartered Property Casualty Underwriter (CPCU) designation. Jeremy believes the best insurance solutions are specialized and transparent, built through adaptability, attention to detail, and a team-first approach. He relishes helping small business owners find coverage that's both affordable and tailored to their individual needs.